Guides
Storm damage roof repair in Wisbech: the first hour, the claim, and the knock
Storm damage roof repair in Wisbech starts before any roofer does. These roofs stand in open fen wind with nothing in front of them, and what you do in the first hour, and what you photograph, decides how the next three months go.
- Why roofs fail here
- The first hour
- Temporary cover
- What insurance covers
- Wear and tear refusals
- The knock at the door
- The permanent repair
Why Wisbech roofs fail at the edges
Wisbech stands on flat, drained fen beside a tidal river. There is no hill, no ridge line, no belt of woodland and very little dense built fabric between the open country and your roof. Wind arrives close to full strength, from whichever direction it likes, and that single characteristic shapes the whole pattern of storm damage here.
Wind damage to a pitched roof is mostly suction rather than pushing. Air accelerating over the ridge and around a gable produces negative pressure, and that pressure is highest at the edges of the roof: the ridge, the verge at each gable end, the hips and the eaves. So the money spent making a roof storm-resistant here belongs at the perimeter rather than in the field of tiles. A mid-slope tile has neighbours holding it down on every side. A verge tile has fresh air on one side and a strip of ageing mortar on the other.
What tends to go first
- Ridge and hip tiles. Traditionally bedded in sand and cement. Mortar loses its grip over decades, and once one ridge tile lifts the wind has a purchase on the rest of the run.
- Verges. The mortar edge at a gable is the most exposed line on the building. On a pantile roof it is also where losing one tile immediately exposes the next one along.
- Eaves underlay and the bottom courses. Driven rain gets under lifted tiles, and the eaves underlay is the last thing between it and the wall plate.
- Flashings and lead. Lead that has lost its clips or wedges lifts in a gust and does not lie back down.
- Anything already compromised. A cracked nib, a corroded nail or a tile somebody stood on last summer.
Water has always been taken seriously here
Wisbech has a long relationship with water that has nothing to do with roofs. A catastrophic flood in 1236 drowned hundreds of people and destroyed whole flocks and herds. A flood in 1978 claimed one life and led to the flood walls and gates that protect the town today.
It would be dishonest to draw a straight line from that history to your roof, and we are not going to. Flood defence and roof defence are separate problems, and a roofer leaning on the town's flood story to sell you tiles is selling rather than advising. What the history does illustrate is the geography behind both: a low, flat, open place beside tidal water where very little stands between the weather and the buildings. The town has invested heavily in the water that arrives from below. Owners are still responsible for the part that arrives from above.
The first hour, in order
- Get everybody away from the outside of the house, especially below the damaged section. Material that has moved once will move again, and a pantile falling two storeys is lethal.
- Do not enter a room with a sagging or bulging ceiling. Shut the door and keep everybody out. Water above plasterboard can bring the whole sheet down at once with no warning.
- Kill the power to any circuit where water is near lights, sockets or the consumer unit.
- Move what you can and contain the water. Electronics and documents out of the way, buckets under the worst of it, something waterproof over whatever cannot be moved.
- Photograph everything before you touch anything. Wide shots, close-ups, the damage inside, and anything that has landed outside. Record the date and the storm name. The most valuable ten minutes you will spend, and the step people skip because they are shaken.
- Call the insurer's emergency line before commissioning anything expensive, as long as that does not mean letting water pour in for hours. Most policies run a 24 hour line and many will authorise emergency work over the phone.
- Get temporary cover organised. If water is coming in, this comes before quotes and before anybody's paperwork.
- Do not go on the roof. Not in the dark, not in the wind, not first thing in the morning to have a look. See emergency roofing.
If it is dangerous, it is not your job
Tiles hanging over a pavement, a chimney that has visibly moved, a lifted section of roof, or anything at risk of falling into a road or onto a neighbour is a call to the emergency services or the council, not something to manage yourself.
If a stack looks out of plumb, treat the rooms beneath it as out of use until somebody competent has been to look at it.
Temporary cover: what it is, and what it should cost
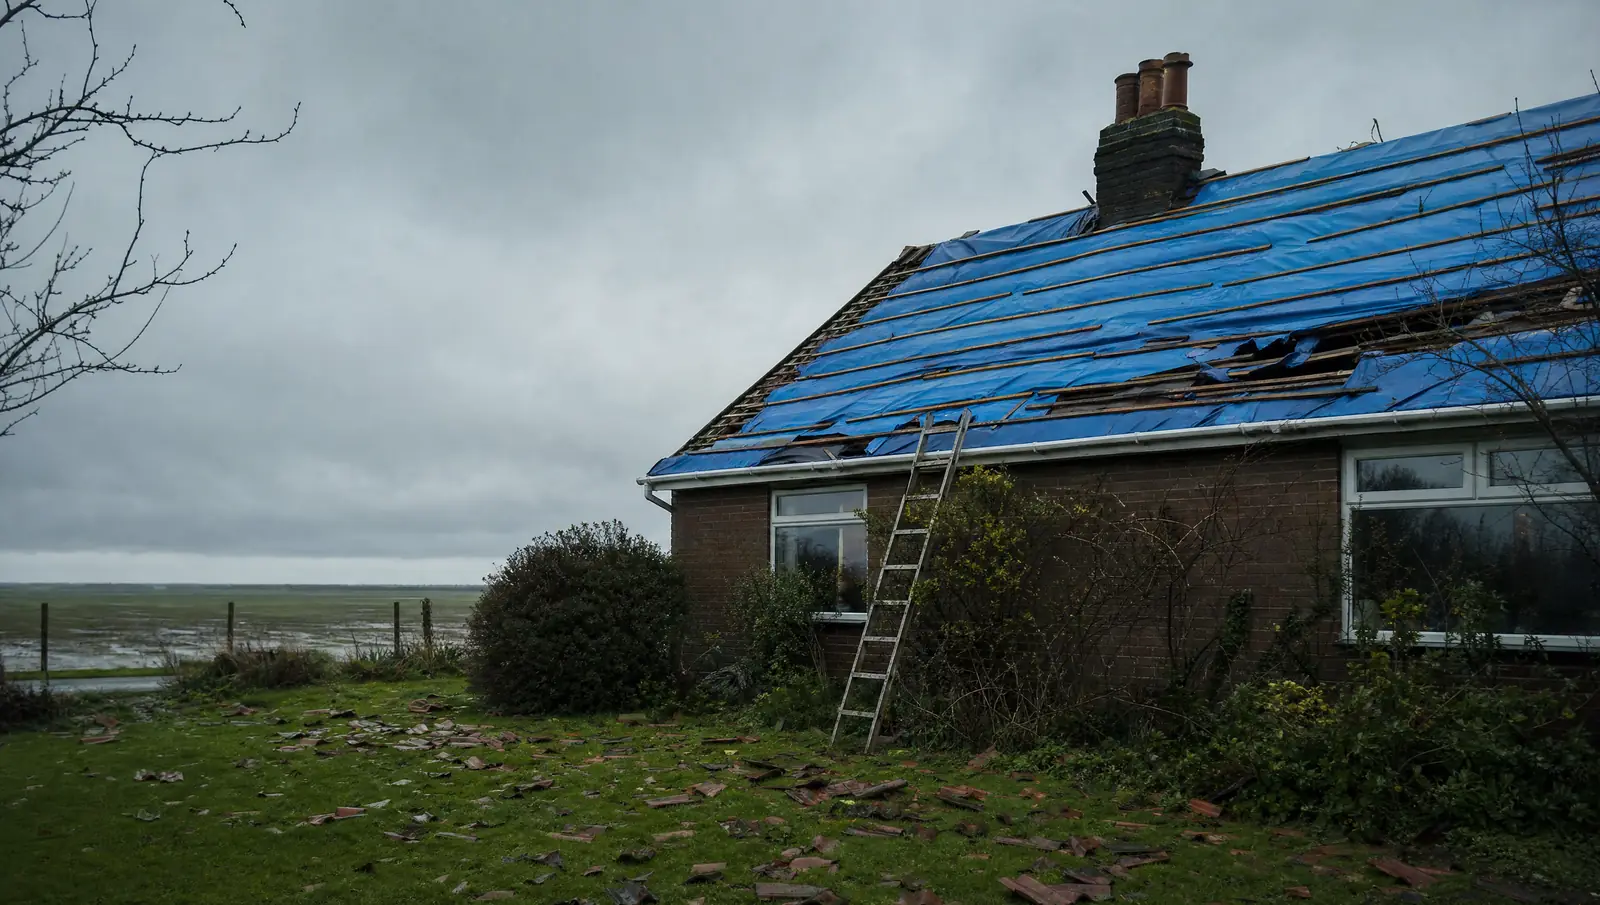
Temporary cover, usually called a tarp, is a heavy duty sheet fixed properly over the damaged area with battens so it stays put in the next round of wind and sheds water off the roof rather than trapping it behind. It is not a bin bag and gaffer tape, and it is not a permanent repair. Done properly it needs safe access, and access is the expensive part: on a bungalow a competent roofer may manage from a ladder or a tower, but two storeys up on a Brink frontage in a gale it is a scaffold or nothing.
Emergency call-out pricing is legitimately higher than planned work, because somebody is dropping other jobs and working in bad conditions. What is not legitimate is a four figure number for a sheet over a hole, or a firm that will only sheet the roof if you sign for the permanent work at the same time. Those are two separate decisions and you are entitled to keep them separate.
- Ask what the cover costs as a standalone job, in writing or by text, before anybody starts.
- Ask whether that cost comes off the permanent repair if you use the same firm. Many will say yes. Get that in writing too.
- Ask how long it is expected to last. Weeks is normal. A whole winter on an exposed gable is optimistic.
- Photograph the damage before the cover goes on. Once it is sheeted, your evidence has disappeared under a tarpaulin.
- Keep the receipt. Emergency work carried out to prevent further damage is normally recoverable on a claim.
What buildings insurance actually covers
Buildings insurance normally covers storm damage. The argument is almost never about whether storm damage is covered in principle. It is about whether what happened to your roof counts as storm damage at all.
What a typical policy includes
- Damage to the structure caused by a storm, usually defined in the policy by wind speed and sometimes extended to heavy snow or torrential rain.
- The resulting water damage inside, such as ceilings and decoration. Your possessions sit under a separate contents section if you have one.
- Reasonable emergency work carried out to prevent further damage, which is the reason you keep the temporary cover receipt.
What it usually excludes
- Gradual deterioration. Insurance is for sudden events, not for maintenance you have deferred.
- Damage to a roof already in poor condition, on the argument that the storm revealed the problem rather than caused it.
- Fences, gates and sometimes outbuildings, frequently excluded outright or capped at a low figure.
- The excess, which on a number of policies is set higher for storm claims than for anything else.
Read the actual policy wording rather than the summary document. The definition of storm written into your policy is the thing the whole claim turns on, and it is not the same from insurer to insurer.
Wear and tear: the reason most claims get refused
Wear and tear is the commonest refusal and it is worth understanding rather than treating as insurers being difficult. Their position is that if a roof was already at the end of its life, the storm did not cause the loss, it exposed it. On a roof still carrying original mortar bedding and original nails after sixty years, that has some force. It also gets applied lazily to roofs where it does not apply at all, and that is where you push back. Two things decide it: your photographs, and how the roofer's report is worded.
- Dated evidence from before and after. Any older photograph showing the roof intact is worth a great deal, and most people have one without realising, in a family photo or an old estate agent listing. Failing that, photographs taken immediately after the storm at least establish the event.
- A report that describes cause, not just condition. A report saying the roof is old, the tiles are worn and a re-roof is recommended hands the insurer its refusal. A report identifying which components failed, in which direction, consistent with wind loading on a named date, and confirming the surrounding covering is otherwise sound, is a completely different document.
- The storm itself. Give the date and the storm name if it had one. Weather records are public and the insurer will check them.
- Consistency. Your account, the photographs and the report should describe the same event. Contradictions get seized on.
Ask a roofer directly whether they are used to writing reports for insurance claims. Plenty are, and it makes a real difference. It is also reasonable for them to charge for the report separately.
If the claim is refused
Ask for the decision in writing with the specific policy clause relied on. Get an independent roofing report that addresses cause rather than condition. Then use the insurer's own complaints process, which is free and which insurers lose more often than people expect.
If that does not resolve it, the Financial Ombudsman Service reviews complaints about insurers free of charge. A first refusal is not the end of the matter.
The knock at the door
After every serious storm a predictable group works door to door across the affected streets. Not all of them are dishonest. Enough are that the pattern is worth knowing cold, and a compact town with older residents in the central streets is where they work.
The pattern
- I noticed from the road that you have tiles missing. Nobody drives past and diagnoses a roof. They are looking for houses to approach, and older people living alone get approached first.
- We are working round the corner and have materials left over. There is no job round the corner and no leftover materials.
- I can go up now and take a look, no charge. Once somebody uninvited is on your roof you have lost control, and on a pantile roof damage gets created as easily as it gets found.
- If you leave it the ceiling will come through. Manufactured urgency, applied hardest to whoever seems most anxious.
- Cash today and I can do it for half. No paper trail, no invoice, no comeback. No legitimate roofer needs your decision inside the hour.
- A mobile number and nothing else, no address on the vehicle, and paperwork carrying no company registration number.
Your cancellation rights
This is the single most useful thing on the page if you have already signed something. When you agree a contract at your own home rather than at a trader's premises, consumer law normally gives you 14 days to cancel for contracts above a low value threshold, and the trader must tell you about that right in writing. Where they fail to, the cancellation period is extended substantially and the failure is itself an offence.
There is a specific trap. If you ask for work to start inside the cancellation period and sign to that effect, you can still cancel but may have to pay for what has genuinely been done. That is exactly what the doorstep operation relies on: get a signature, start immediately, then invoice for a part-finished job.
If you have already paid and it has gone wrong, contact Citizens Advice, who pass reports to Trading Standards. Payments over £100 by credit card may carry additional protection through the card provider.
- Never let anybody onto your roof who arrived uninvited.
- Never pay cash up front to somebody who knocked on your door.
- Never sign anything on the doorstep on the day.
- If they are genuine, they will still be genuine tomorrow. Take the details and check them properly, or approach firms yourself instead. Our quote comparison is one way to do that, and how it works sets out exactly what happens to your details.
From temporary cover to a permanent repair
Once the water has stopped the pressure comes off, and that is exactly the moment to slow down rather than speed up.
- Get the temporary cover on, the same day if water is coming in.
- Notify the insurer even if you are not sure you will claim. Late notification is itself a reason claims get reduced or declined.
- Get the damage assessed and photographed, and if you are claiming, get the report worded around cause rather than condition.
- Get two or three quotes. Storm work is exactly when people accept the first number because they are rattled, and exactly when they should not.
- Check the whole roof while there is access. If a scaffold is going up anyway, dealing with the rest of the ridge, the verges and the flashings costs very little next to doing it separately in two years.
- Only then agree the work in writing, with the materials, the fixing specification and the guarantee all stated.
On an exposed site the sensible upgrade at this point is the perimeter. Mechanically fixed ridge and verge systems hold up far better than mortar bedding and remove the failure that most commonly starts a storm claim here. Pantile roofs covers what to ask for.
If the storm has exposed a covering that is genuinely finished, that is a bigger conversation. Guide ranges put a full re-roof at roughly £5,500 to £9,500 on a terraced house and £7,000 to £13,000 on a semi-detached. See roofing costs and roof repair cost.
For the work itself see roof repairs and, for the stack, chimney repairs. If the building is listed or in a conservation area, read listed buildings and conservation areas before agreeing materials, because like for like may not be your decision. The checks in how to choose a roofer are worth more in the week after a storm than at any other time.
Frequently asked questions
Usually yes, where the damage was caused by a sudden storm event. What is commonly excluded is damage to a roof that was already worn out, on the argument that the storm revealed the problem rather than caused it.
Emergency work carried out to prevent further damage is normally recoverable as well, so keep the receipt for any temporary cover.
Because the town sits on flat open fen with nothing to slow the wind down, and because wind damage to a pitched roof is mostly suction rather than pressure. The suction is strongest at the edges of the roof, so the ridge, the verges, the hips and the eaves take the highest loads.
Those are also the places where older roofs rely on mortar bedding, which is why mechanically fixed ridge and verge systems make a real difference on an exposed site.
It depends on your policy, and it is the detail worth checking before you claim rather than after. Many insurers use a stated wind speed threshold, some extend the definition to heavy snow or torrential rain, and some leave it deliberately loose.
Weather records for the date are public and the insurer will look them up, so give the exact date and the storm name if it had one.
If water is actively coming in, yes. Policies expect you to take reasonable steps to prevent further damage, and sitting on hold while a ceiling fills up can count against you.
Call the emergency line if you can, keep the cost proportionate to the problem, and keep the receipt and the photographs.
Thank them, take no action, and do not let them onto the roof. If you are genuinely worried, look from the ground yourself or from an upstairs window at a neighbouring property, then approach a firm you found rather than one that found you.
Nobody diagnoses a roof from a moving vehicle. If material is at risk of falling into a road or onto a pavement, that is a call to the council or the emergency services, not to the person on your doorstep.
Normally yes. Contracts agreed away from a trader's business premises usually carry a 14 day cancellation right, and the trader must give you written notice of it. Where they fail to, the period is extended substantially.
If work has already started at your request you may owe for what has genuinely been done, which is why signing to start immediately is the thing to avoid. Citizens Advice can confirm where you stand on your particular contract.
No. Ask for the refusal in writing with the specific policy clause relied on, get an independent roofing report that addresses cause rather than condition, and go through the insurer's complaints process.
If you are still unhappy after that, the Financial Ombudsman Service reviews complaints about insurers free of charge.
After widespread damage every roofing firm in the area is answering calls at once, so temporary cover within a day or two and a permanent repair some weeks later is a realistic expectation rather than a poor service.
Flag the job as an emergency when you get in touch. Genuine water ingress gets prioritised over inspections and estimates.
Get quotes from Wisbech roofers
Tell us your postcode and what needs doing. We pass it to vetted roofing firms covering that part of Wisbech, and they come back to you directly with quotes.
- Takes about a minute
- No cost to you, ever
- You choose who to speak to, and you can say no to all of them
Compare Wisbech roofers
Answer four questions. We pass your job to vetted roofers who cover your postcode, and they come back to you with quotes. No charge, no obligation.
We pass your details only to roofing firms that cover your postcode, so they can quote. We never sell your details on for other purposes. See our privacy notice.
Find out what your roof should cost
Compare quotes from vetted Wisbech roofers, or call us and we will point you at the right sort of firm for the job.